
The key distinction: a checkout wallet is not a cash account
An Apple Pay button tells you how the deposit can be authorised. It does not, by itself, identify where the operator will send a withdrawal. Treat the deposit interface and payout instructions as separate pieces of evidence. Before depositing, ask whether this particular card-backed payment permits withdrawal and what the receiving account will be.
Apple Pay uses tokenisation for card payments. As a result, transaction records can show account digits associated with a token rather than the last digits printed on the physical card. That difference is not automatically a payment error. It can, however, create confusion when the cashier lists a masked destination you do not immediately recognise.
Match the transaction without exposing sensitive details
If the operator asks about a masked card, check the relevant card details in your device wallet and compare them with the original deposit record. Explain that the payment was made using Apple Pay. Do not guess that an unfamiliar suffix belongs to another account, and do not send the full card number or security code to ordinary support chat.
A replacement device or re-added card can complicate the record because the token associated with a payment may differ from your current display. Tell support what changed and ask how it verifies ownership in that situation. Provide evidence only through a confirmed secure channel and redact unrelated information if the operator permits it.
Ownership remains important even when the device is shared. The gambling account holder should use an appropriate payment source in their own name. Device access and successful biometric authorisation are not substitutes for the operator’s responsibility to establish who owns the money and where it can lawfully be returned.
Three answers the cashier must give you
- Name the actual outgoing route: supported card credit or another verified account.
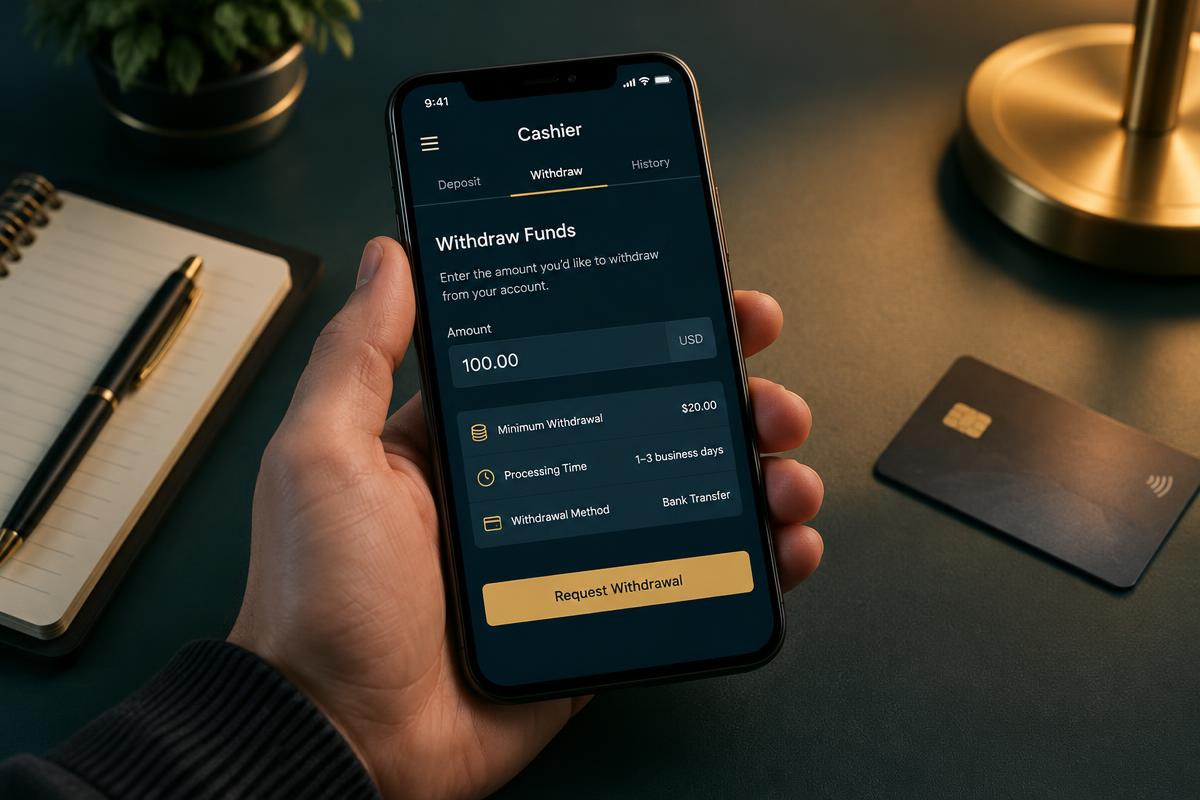
- Show the minimum, maximum and any fee for that route.
- Explain when the delivery estimate begins and what can delay approval.
Where the operator supports a payout to the underlying card, the issuer and processing arrangement still matter. A debit card that works for deposits is not necessarily enabled for every outgoing payment service. The Visa Fast Funds guide explains one specific card capability; it should not be applied indiscriminately to every card in an Apple Pay wallet.
If no compatible card payout exists, the operator may offer a bank destination after verifying ownership and considering return-to-source requirements. Establish that process before depositing where possible. The debit-card guide provides a broader comparison, while Google Pay covers a similar checkout-wallet distinction without making the two services interchangeable.
Why a quick deposit tells you little about withdrawal time
A deposit can receive a rapid authorisation response. A withdrawal needs the operator to recognise a withdrawable balance, perform applicable checks and issue an outgoing payment. These are different workflows, even if the cashier displays the same card artwork. Never use the time it took to fund an account as evidence of the time required to cash out.
After release, card-credit processing and issuer posting can introduce their own timing. Check whether the estimate uses calendar days or business days and whether a cut-off applies. Weekend availability for authorising deposits does not prove that a manual withdrawal review or receiving-account process will run on the same schedule.
Keep the request timestamp, approval message and payment reference. If support says “completed”, ask whether this means released to the processor or confirmed received. Precise wording helps you choose whether to wait within the quoted window, ask the operator to trace a payment or approach the issuer with an appropriate reference.
A lost phone need not mean lost winnings
If a device is lost, follow the device and card providers’ official security procedures promptly. Then tell the operator about any effect on the original payment method. Do not assume that removing a card from a wallet cancels a pending casino withdrawal, and do not rely on an old device entry as proof that the receiving card is still active.
If the underlying card has expired, been replaced or closed, ask the issuer whether it can receive or redirect the expected credit. Some replacements may be linked internally, but that is not a universal rule. The operator may need an alternative verified destination if the original route rejects the payment.
An unresolved payment is not a reason to add someone else’s card or open a second gambling account. Keep the existing case intact and ask for written instructions. An agreed ownership-check process is safer and usually easier to trace than several new transactions made in an attempt to force the cashier to change.
Security features do not replace gambling safeguards
Biometric authorisation can help protect the deposit interaction, but it does not assess whether you can afford gambling or whether a withdrawal term is appropriate. Check the Gambling Commission register for the operator’s legal entity and domain. For Great Britain, a familiar device payment option does not make an unlicensed gambling business suitable.
Age and identity checks must precede gambling, although further payment-ownership or anti-money-laundering enquiries can arise. If additional evidence is requested at withdrawal, ask what is needed and why. Never disclose a device passcode, banking password or one-time security code to somebody claiming to accelerate a payout.
For current offers, Gambling Commission rules cap wagering requirements at ten times bonus funds. A £15 bonus with a 10× requirement means £150 in qualifying turnover, not a guaranteed remaining balance. Check exclusions, permitted stakes and expiry. Declining the bonus can remove promotional complexity, but it does not eliminate routine payment checks or ensure an instant transfer.
Follow the receiving account when checking costs or delays
Check the currency of the gambling account, the currency sent and the account that receives the card credit. If conversion is involved, establish who applies it. The absence of a charge for using the device wallet does not prove that the operator or receiving institution imposes no fee elsewhere in the journey.
When a released payment is missing, ask the operator for a trace reference appropriate to the card transaction. An issuer may need more than the casino’s internal withdrawal number. Supply the amount, currency and release date, but keep full card credentials out of ordinary messages. Request written confirmation if the payment has been rejected and returned.
If the operator fails to resolve the issue, use its formal complaints procedure with a concise timeline and supporting records. Eligible disputes may progress to the named alternative dispute resolution service after eight weeks or earlier deadlock. Pause gambling rather than cancelling a withdrawal and risking the balance while you wait.
Frequently asked questions
Can winnings be paid into an Apple Pay balance?
Why do the card digits look different?
Will buying a newer phone speed up withdrawals?
Problems players reported, and how to avoid them
These are attributed player reports, not findings against the operators. Each links to its source and a practical next step when a withdrawal is delayed.
Val, Trustpilot, 29 May 2025: Val alleged deposits worked but the account was blocked when attempting to withdraw. No resolution visible in retrieved review.
Page update log
- PublicationPublished 13 November 2026. Editorial by Alex Whitmore.